Building in Southwest Florida Starts With a Different Kind of Financing
Sep 16, 2026
Paradise Coast Mortgage
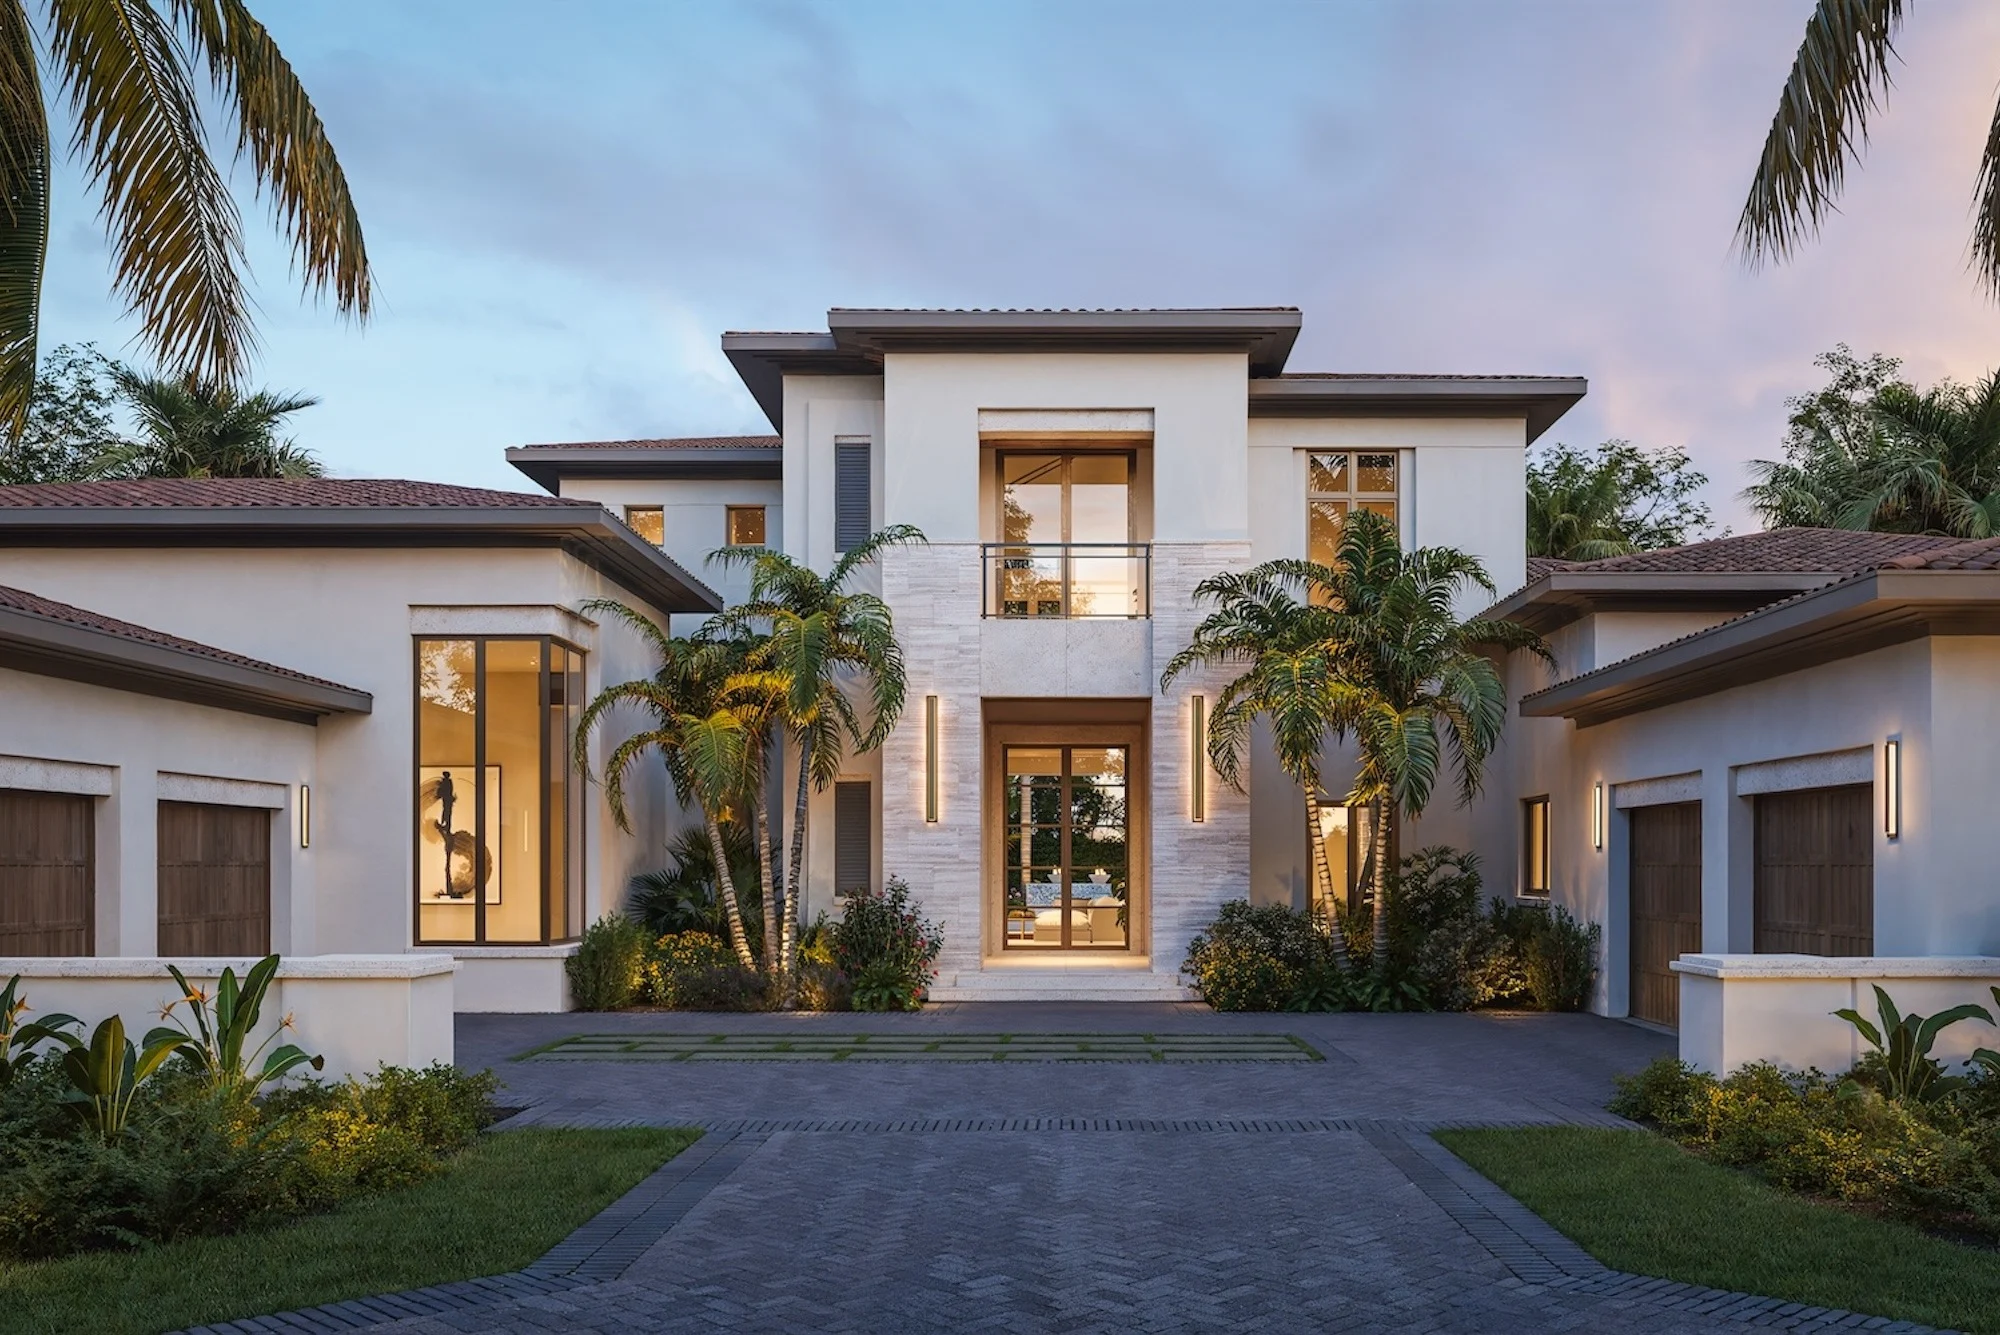
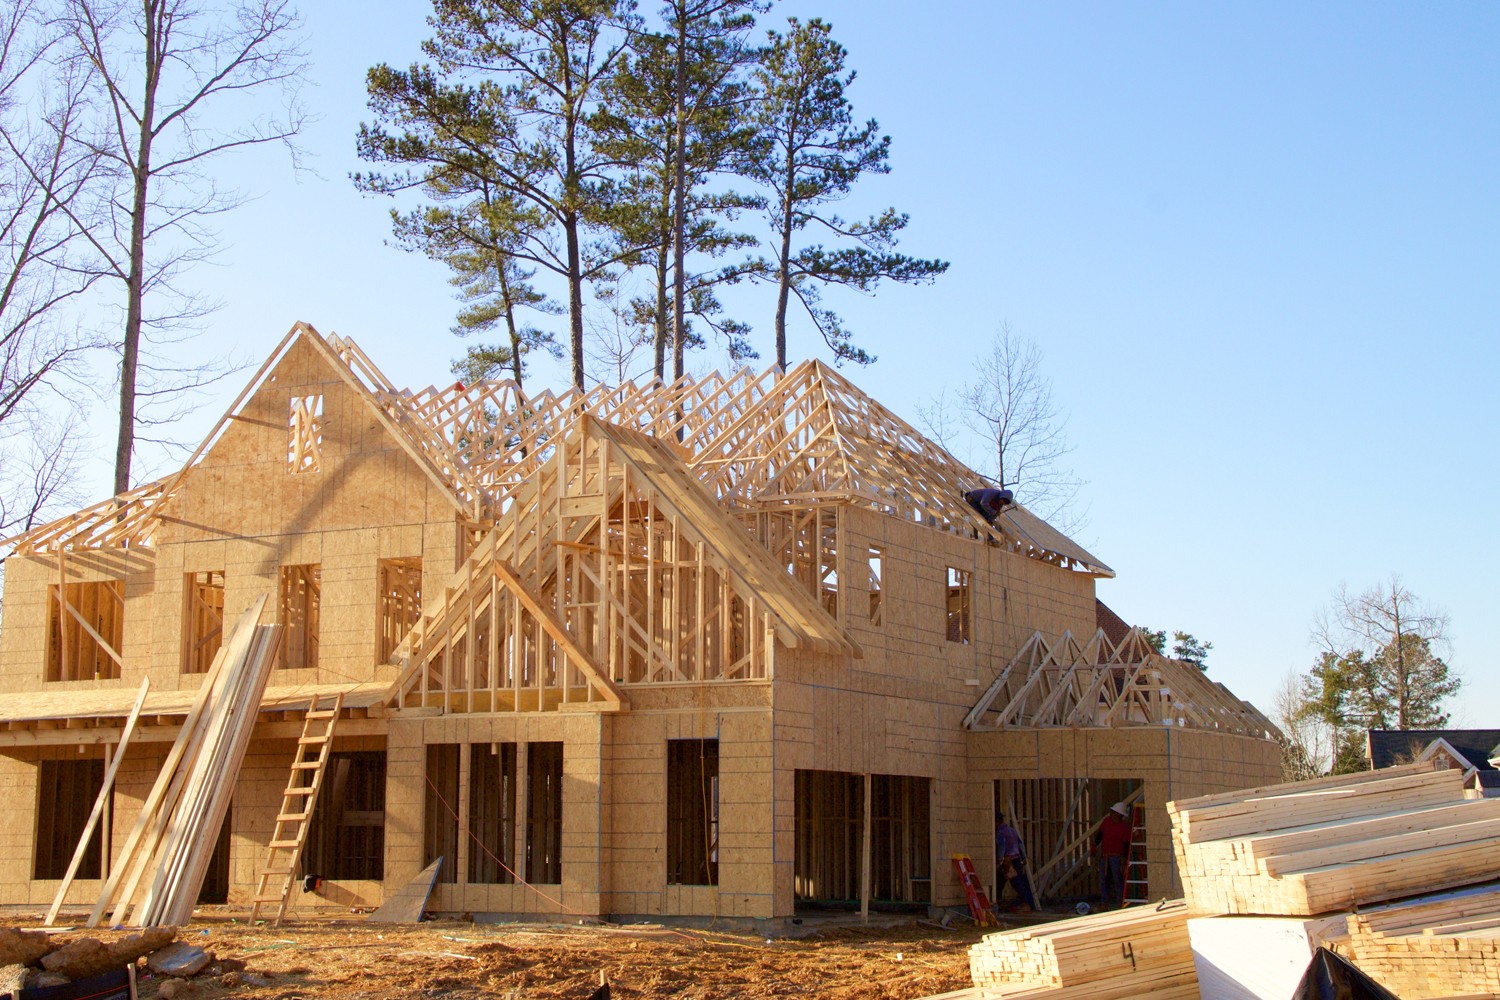
Southwest Florida has seen significant new construction activity across Collier and Lee County, and a meaningful number of buyers are choosing to build rather than purchase existing inventory. For those buyers, the financing conversation starts earlier and involves more moving parts than a standard home purchase loan.
What a Construction Loan Is
A construction loan is a short-term financing product that funds the cost of building a home. Unlike a standard mortgage, which is disbursed in a lump sum at closing, a construction loan releases funds in stages called draws as construction milestones are completed. The lender sends an inspector to verify that each phase of work has been completed before releasing the next draw to the builder.
During the construction period, borrowers typically pay interest only on the funds that have been drawn down rather than on the full loan amount. This keeps the monthly obligation manageable while the home is being built.
The Construction-to-Permanent Structure
The most common approach for buyers building a primary or secondary residence in Southwest Florida is a construction-to-permanent loan, sometimes called a one-time close. This product combines the construction financing and the permanent mortgage into a single loan with one closing and one set of closing costs.
At the end of the construction period, once the certificate of occupancy is issued, the loan automatically converts to a standard mortgage with a fixed or adjustable rate based on the terms agreed to at the original closing. The buyer locks the permanent rate at the time of the initial closing, which removes rate risk during the construction period.
What Lenders Evaluate
Construction loan underwriting looks at everything a standard mortgage underwriting reviews, the borrower's income, credit, and assets, plus additional factors specific to the construction project. These include the credentials and track record of the builder, the appraised value of the completed home based on the plans and specifications, and the construction timeline and draw schedule.
A builder who is not approved by the lender or who cannot provide adequate documentation of their licensing and insurance can create complications that delay or prevent loan approval. Buyers should confirm their builder's lender approval status before signing a construction contract.
What Buyers Should Prepare For
Construction timelines in Southwest Florida can be affected by permitting, weather, and subcontractor availability in ways that extend the construction period beyond initial estimates. Most construction loans have terms of six to twelve months, and extensions are available but sometimes come with additional costs.
At Paradise Coast Mortgage, we work with buyers and builders throughout the construction process to ensure draws are processed efficiently and the conversion to permanent financing happens smoothly.